
The Bank of Canada has not raised rates since October 2025. Prime has not moved all year. So why did your fixed quote go up? The answer is a number almost nobody watches.
October 23, 2026
If you are shopping for a home in Mississauga or anywhere in the GTA right now, you have probably noticed something confusing. Headlines say the Bank of Canada is holding rates steady and it is. The Bank’s overnight rate has been 2.25% since October 2025. The prime rate at the chartered banks has sat at 4.45% all year.
And yet the fixed mortgage rate your lender quoted you last month is higher than the one they quoted in the summer. Here is why.
Three rates that matter to a buyer. Only one of them has moved.
Fixed and variable follow two completely different things
This is the single most useful thing to understand about mortgage pricing, and most buyers are never told it.
A variable rate moves with the prime rate, and prime moves with the Bank of Canada. When the Bank cuts, prime usually falls, and your variable rate falls with it. That is the connection everybody knows about.
A fixed rate does not work that way. Lenders fund a five-year fixed mortgage by borrowing in the bond market, so they price it off the yield on Government of Canada bonds of a similar length. When bond yields rise, fixed mortgage rates rise regardless of what the Bank of Canada is doing.
Definitions from the Financial Consumer Agency of Canada; rates from the Bank of Canada.
So what actually happened
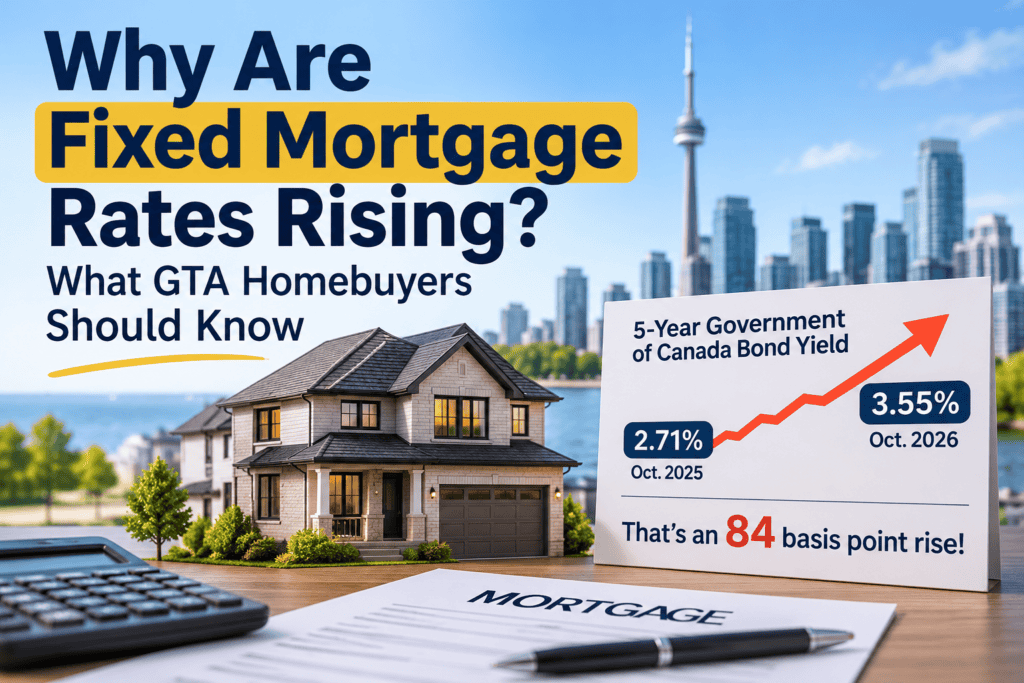
The Government of Canada five-year benchmark bond yield was 2.71% in mid-October 2025. By mid-October 2026 it was 3.55%. That is a rise of 84 basis points 0.84 of a percentage point in a single year.
Over the same twelve months the Bank of Canada’s overnight rate did not move at all. Neither did prime. Bond yields rise when investors expect more inflation over the coming years, or when they want to be paid more for lending to the government over that time. Neither of those things requires the Bank of Canada to do anything.
That one chart explains almost every confused conversation buyers are having right now.
Bank of Canada published data. The bond yield moved; the other two did not.
What 84 basis points actually costs you
Numbers make this concrete. Take an $800,000 purchase with 20% down. That leaves a $640,000 mortgage over a 25-year amortization.
At 4.00% the payment is about $3,367 a month. At 4.50% it is about $3,542 roughly $176 more a month, or $10,542 over a five-year term. At 5.00% it is about $3,722 about $356 more a month than at 4.00%, or $21,345 over five years.
These are principal and interest only. They do not include property tax, condominium fees, heat or insurance, and they are not a quote — your actual rate depends on your lender, your term, whether the mortgage is insured, and your own credit and income.
Illustrative calculation. Speak to a licensed mortgage professional for a real number.
And remember you are not qualified at the rate you pay
The Financial Consumer Agency of Canada is clear on this: banks must qualify you at the higher of 5.25% or the interest rate you negotiate with your lender plus two per cent. That applies to insured and uninsured mortgages alike.
So if your lender quotes you 4.50%, you are being tested at 6.50%. How much you can borrow is set by that test, not by the rate you will actually be paying. It is worth knowing that before you start looking, not after you have fallen in love with a house.
| THE HONEST TAKE
If your mortgage quote went up and you have been watching the Bank of Canada, you have been watching the wrong number. The Bank’s rate has not moved since October 2025. Prime has not moved all year. The number that moved is the Government of Canada five-year bond yield, and that is the one fixed mortgage rates are priced off. This also means the October 28 Bank of Canada announcement may not change your fixed quote at all. Whatever the Bank does on Wednesday affects variable rates and prime. A fixed rate will respond to what bond investors think about inflation over the next five years, which is a different question and often moves in a different direction. Get your rate hold in writing, and know how long it runs. Most lenders will hold a rate for 90 to 120 days once you are pre-approved. In a market where the five-year yield has moved 84 basis points in a year, that hold is worth real money — and it protects you if rates rise while you shop, without locking you out if they fall. Do not let the stress test surprise you at the end. Banks must qualify you at the higher of 5.25% or your negotiated rate plus two per cent, for insured and uninsured mortgages alike. So if you are quoted 4.5%, you are being tested at 6.5%. The amount you can borrow is set by that test, not by the rate you will actually pay. The practical move is to shop the term, not just the rate. A shorter fixed term often prices differently from a five-year, and a variable can be converted to a fixed later with most lenders. Which one is right depends on how long you plan to hold the property and how much payment certainty you need — not on a forecast nobody can make reliably. |
SOURCES
Official sources
- Bank of Canada — Government of Canada benchmark bond yield, 5 year (the series that drives fixed mortgage rates) https://www.bankofcanada.ca/valet/observations/BD.CDN.5YR.DQ.YLD/json?start_date=2025-10-01
- Bank of Canada — prime rate series https://www.bankofcanada.ca/valet/observations/V80691311/json?start_date=2026-01-01
- Bank of Canada — key interest rate: target for the overnight rate https://www.bankofcanada.ca/core-functions/monetary-policy/key-interest-rate/
- Bank of Canada — Canadian interest rates and monetary policy variables https://www.bankofcanada.ca/rates/interest-rates/
- Financial Consumer Agency of Canada — Preparing to get a mortgage (the stress test rule) https://www.canada.ca/en/financial-consumer-agency/services/mortgages/preparing-mortgage.html
- Financial Consumer Agency of Canada — Choosing a mortgage that is right for you (fixed versus variable) https://www.canada.ca/en/financial-consumer-agency/services/mortgages/choose-mortgage.html
- Financial Consumer Agency of Canada — Mortgages overview https://www.canada.ca/en/financial-consumer-agency/services/mortgages.html
- Toronto Regional Real Estate Board — Market Watch (current GTA sales and price data) https://trreb.ca/market-news/market-watch/
Gagan Verma, Residential REALTOR of Royal LePage Signature Realty, Brokerage, Independently Owned and Operated · 200-30 Eglinton Ave W, Mississauga, ON L5R 3E7 · info@realtorgagan.com · 647-910-1111
This article is general information for homebuyers and is not mortgage, financial, legal or tax advice. Interest rates change daily and the figures shown are as at the dates stated. The payment examples are illustrative calculations, not quotes or offers of credit. Speak to a licensed mortgage professional about your own situation. Not intended to solicit buyers or sellers currently under contract with another brokerage.